GS-III – Economy | Manufacturing | Global Value Chains | Industrial Ecosystems
Why in News?
- SpaceX: SpaceX’s reported efforts, in July 2026, to remove Chinese-made components from its supply chain capture a new phase in the restructuring of global production.
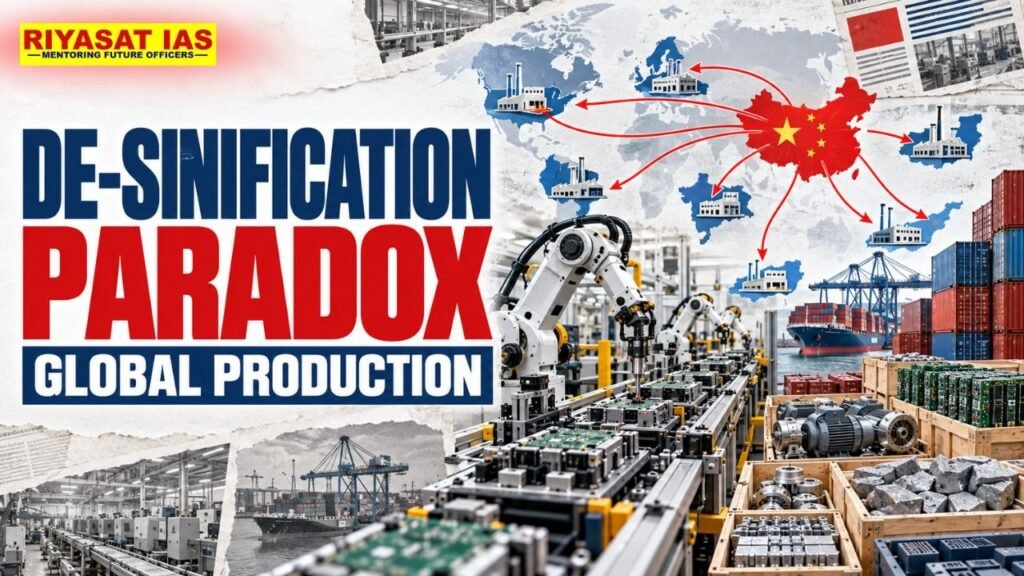
- Changing Nature of Production: The challenge now is not just about where a product is assembled, but how it could possibly be made. It is much more about what is several steps below the end manufacturer.
- Supply Chains: Finder firms around the world increasingly need to locate, replace and verify suppliers downstream in their convoluted production networks.
- Industrial Ecosystem: Moving a factory may be relatively straightforward; removing an industrial ecosystem from the production process is not.
The Other Side of De-Sinification
- Two-sided Challenge: The ecosystem problem is not confined to foreign firms seeking to reduce their exposure to China.
- Chinese Companies: Chinese companies expanding overseas increasingly confront it from the opposite direction.
- Foreign Firms: Foreign firms struggle to disentangle themselves from Chinese suppliers and capabilities.
- Chinese Firms: Chinese firms must decide how much of the industrial ecosystem that supports their competitiveness at home can be carried abroad and how much must be recreated locally.
- Moving Target: While foreign firms aim to be less reliant on China, China is gaining in sectors where it has long depended on Western technology.
China’s Changing Industrial Capabilities
- CXMT: Memory-chip maker CXMT has emerged as the world’s fourth-largest producer of DRAM chips.
- Advanced Technologies: China continues to lag behind global leaders in advanced memory technologies and remains reliant on access to foreign chipmaking equipment.
- External Dependencies: Chinese firms are simultaneously working to reduce their own external dependencies.
- Implication: Attempts to reduce exposure to China are therefore taking place against a moving target.
The Reverse Challenge for Chinese Manufacturers
- Overseas Expansion: Chinese manufacturers venturing overseas confront a form of de-Sinification from the opposite direction.
- Beyond Assembly: Their internationalisation increasingly involves more than establishing final-assembly plants.
- BYD and Xpeng: The competitiveness of companies such as BYD and Xpeng rests partly on dense networks of component makers, engineering capabilities and production relationships developed within China.
- Three Choices: Moving a factory abroad creates a choice:
- Take existing suppliers along.
- Cultivate new local suppliers.
- Combine the two.
- Different Outcomes: Each route carries different costs and produces a different degree of genuine localisation.
The Challenge Beyond Factories
- BYD in Europe: As BYD builds manufacturing capacity in Hungary, the company is also developing relationships with European suppliers.
- Xpeng: Xpeng has chosen another route, contracting Canadian automotive supplier Magna to assemble its vehicles in Austria.
- Common Problem: The two approaches differ, but they expose the same underlying problem: producing outside China is easier than reproducing outside China the ecosystem that made production in China efficient in the first place.
- Industrial Ecosystem: These ecosystems consist of more than identifiable suppliers.
- Accumulated Capabilities: They embody:
- Accumulated relationships between firms.
- Specialised skills.
- Tooling and production knowledge.
- Logistics networks.
- The ability of suppliers to respond quickly when designs or production volumes change.
- Repeated Interaction: Numerous advantages of these may be constructed through repeat engagement as against contracts.
- Wider Dependence: Swapping out a single Chinese supplier may not dismantle dependence on the broader Chinese production chain.
- Portability: Transplanting a Chinese factory abroad does not necessarily relate to the capabilities surrounding it.
Two-Sided Character of De-Sinification
- Foreign Firms: Foreign firms attempting to reduce their exposure to China confront the depth of China’s integration into their production networks.
- Chinese Firms: Chinese firms going global confront the difficulty of reproducing abroad the ecosystem on which their competitiveness depends.
- Common Challenge: One side is trying to disentangle itself from an ecosystem; the other is trying to make that ecosystem portable.
- Core Insight: Both discover that changing the location of production is easier than changing the capabilities and relationships that sustain it.
What India Needs to Note and Build
- Opportunity for India: The reorganisation of production is already creating openings.
- TDK: Japan’s TDK has expanded its battery production in Haryana, deepening an Indian manufacturing base that it has been developing as part of its broader China-plus-one strategy.
- Murata Manufacturing: Murata Manufacturing is expanding its manufacturing presence in India.
- Production Ecosystems: These investments show that India is beginning to receive parts of production ecosystems previously concentrated in China.
- Beyond Individual Factories: Making the most of this opening requires more than attracting individual factories.
- Domestic Suppliers: India needs domestic suppliers capable of meeting demanding cost, quality and delivery standards.
- Supporting Capabilities: India also needs reliable logistics, skilled workers and access to critical inputs.
- Domestic Linkages: The test is whether new investments progressively deepen linkages with Indian firms and bring specialised capabilities and intermediate production into the domestic economy.
- Chinese Investment: The same principle should inform Chinese investment: its value should be judged partly by the capabilities and supplier networks it develops locally.
- Industrial Ecosystem: India’s opportunity is to convert the movement of factories into the gradual accumulation of an industrial ecosystem of its own.
Way Forward
- Beyond Factory Location: The reorganisation of global production should focus not only on where factories are located but also on whether the ecosystems behind those factories can be dismantled, transferred or rebuilt.
- Domestic Capabilities: India needs domestic suppliers capable of meeting demanding cost, quality and delivery standards.
- Industrial Linkages: New investments should progressively deepen linkages with Indian firms and bring specialised capabilities and intermediate production into the domestic economy.
- Supplier Networks: The value of investment should be linked partly to the capabilities and supplier networks it develops locally.
- Industrial Ecosystem: India should convert the movement of factories into the gradual accumulation of an industrial ecosystem of its own.
Conclusion
- Deeper Shift: The emerging geography of global production will be shaped by more than decisions over where to locate factories.
- Industrial Ecosystems: It will depend on whether the ecosystems behind those factories can be dismantled, transferred or rebuilt.
- Real Test: De-Sinification will almost certainly spout visible words about factory locations and investment announcements, but its real test lies further into the production system.
- Core Challenge: Compared with factories, industrial ecosystems based on aggregated levels of capability and relationships are not terribly mobile.
UPSC Mains Practice Question
Q. De-Sinification is not merely about shifting factories from one country to another but also about dismantling, transferring or rebuilding the industrial ecosystems behind them. Discuss the issue within global production networks and India’s manufacturing opportunity
 Ravi Raaz
 Hassan Khan
 Shadab Ali